California’s winter weather can be unpredictable. A few relatively quiet weeks can quickly give way to days of heavy rain, strong winds, localized flooding, power outages and saturated ground.
For homeowners, that can mean roof leaks, fallen trees and water where it doesn’t belong. For farmers, ranchers and agribusinesses, the stakes can be even higher: flooded fields, inaccessible roads, damaged equipment, livestock concerns, downed power, compromised buildings and interruptions during critical operations.
With El Niño and the possibility of significant winter weather once again part of the conversation, early fall is a good time to prepare — while the ground is dry and before everyone is scrambling ahead of the first major storm.
Here are some practical steps California homeowners and agricultural businesses can take now.
1. Start at the Top: Inspect Roofs, Barns and Agricultural Buildings
A small leak today can become a major problem during several consecutive days of rain.
Homeowners should inspect roofing, flashing, vents, skylights and other potential entry points for water. On farms and ranches, don’t stop at the residence. Check barns, shops, equipment buildings, storage facilities, offices and other structures as well.
Look for loose roofing materials, damaged panels, deteriorated seals and areas that have leaked during previous storms.
Pay particular attention to buildings protecting expensive machinery, feed, supplies or other property that could suffer significant damage from water intrusion.
2. Clean Gutters, Drains, Ditches and Culverts
Good drainage is important around any home. On agricultural property, it can be critical.
Clear leaves, dirt and debris from gutters and downspouts around homes and buildings. Make sure downspouts move water away from foundations rather than allowing it to collect alongside structures.
For farms and larger properties, inspect drainage ditches, culverts, field drains and other channels that move stormwater through or away from the property.
A partially blocked culvert may not seem important on a dry September afternoon. After hours of heavy rain, it can become a very different story.
3. Think About Where the Water Will Go
Walk your property before the rain arrives and ask a simple question: If we get several inches of rain, where is that water going to go?
Look for low spots, previous areas of standing water, erosion, blocked drainage paths and places where runoff could reach buildings.
On agricultural properties, consider access roads as well. A home, barn or operation that isn’t flooded can still have a serious problem if employees, feed trucks, veterinarians, suppliers or emergency vehicles can’t reach it.
If there were trouble spots during previous wet winters, now is the time to address them.
4. Inspect Trees Before Saturated Soil and Wind Arrive
Winter storms don’t only bring rain. Saturated ground combined with strong winds can topple trees and bring down large branches.
Inspect trees around homes, barns, shops, vehicles, equipment storage areas, livestock areas, fences and utility lines.
Dead limbs, damaged trees and trees that are already leaning deserve particular attention. When appropriate, have questionable trees evaluated by a qualified professional.
5. Get Pumps and Generators Ready Now
If your home or agricultural operation depends on a sump pump, drainage pump, well pump or generator, don’t wait for a storm to discover that it doesn’t work.
Test equipment now. Check fuel, batteries, hoses, connections and maintenance items, and make sure the people who may need the equipment know how to operate it safely.
For agricultural businesses, think through what happens if commercial power is unavailable for several hours — or several days.
Which operations stop? What happens to irrigation or drainage pumps? Refrigeration? Ventilation? Lighting? Water systems? Livestock operations?
A generator that hasn’t been started in two years shouldn’t be considered an emergency plan until it has actually been tested.
6. Protect Farm Machinery and Mobile Equipment
Tractors, implements, forklifts, utility vehicles and other agricultural equipment represent a substantial investment.
Whenever practical, move valuable equipment away from low-lying areas that have flooded in the past and store machinery under appropriate cover.
Consider access, too. Equipment parked safely on Friday isn’t very useful on Monday if the road leading to it has become impassable.
Fall is also a good time to inspect tires, batteries, lights and other basic items on vehicles and equipment that may be needed during poor weather.
7. Have a Plan for Livestock
For farms and ranches with animals, winter storm preparation should include more than buildings and machinery.
Consider whether livestock areas have adequate drainage, whether animals can be relocated if an area floods and whether feed and clean water will remain accessible during prolonged bad weather.
Also think about transportation. If roads become flooded or muddy, could you still reach the animals? Could a veterinarian reach them?
Those are much easier questions to solve before the storm.
8. Secure Materials That Wind or Water Can Move
Strong winds and moving water can turn ordinary items into hazards.
Secure outdoor furniture and loose items around homes. On farms and commercial properties, inspect portable equipment, empty containers, building materials, temporary structures and other objects that could move during a storm.
Also consider materials stored directly on the ground. Pallets, supplies, feed and other valuable property may benefit from being moved or elevated if water has entered the area previously.
9. Prepare for Employees and Business Interruptions
Agribusiness owners have another consideration homeowners generally don’t: employees.
Decide ahead of time who is responsible for storm preparation, who has authority to shut down operations and how employees will be contacted if roads or facilities become unsafe.
Make sure emergency contact information is current and that employees understand they should never risk driving through flooded roadways simply to reach work.
It is also worth thinking through how the operation would function if a key building, piece of equipment, utility service or access road became unavailable.
10. Photograph Your Property Before Winter
This may be the easiest item on the entire list.
Take your phone and walk around the property.
For homeowners, photograph rooms, furniture, appliances, electronics, improvements and the exterior of the home.
For farms and agribusinesses, photograph buildings, machinery, vehicles, tools, equipment, inventory and other significant property. Record serial numbers or identifying information for particularly valuable equipment when practical.
A short video walking through a shop or equipment building can capture a surprising amount of information in just a few minutes.
Keep copies somewhere safe and preferably backed up online rather than stored only on a phone or computer located at the property.
11. Review Your Insurance Before You Need It
Winter storm preparation isn’t complete without looking at your insurance.
Homeowners should review dwelling limits, personal property coverage, deductibles and important exclusions.
Farmers, ranchers and agribusiness owners may have considerably more to review, including buildings, farm machinery and equipment, commercial vehicles, inventory, liability exposures and potential loss of income following a covered event.
If you have purchased equipment, added a building, expanded an operation or made significant improvements since your last insurance review, make sure those changes are reflected in your current coverage.
And there is one issue that deserves special attention before a wet winter: flooding.
Damage caused by rising surface water or flooding is generally treated differently from damage caused by wind or rain entering through storm damage, and standard homeowners and commercial property policies commonly exclude flood damage.
Don’t wait until a major storm is approaching to find out what your policy does — and doesn’t — cover.
Preparation Is Part of Managing Risk
No one knows exactly what California’s winter will bring to a particular home, farm or community.
That’s really the point of preparing.
You don’t have to know whether the next storm will bring one inch of rain or six to know that clearing a drain, repairing a roof, testing a generator and moving expensive equipment out of a known flood-prone area are worthwhile precautions.
At Scurich Insurance Services, we work with homeowners, farmers, ranchers and agricultural businesses throughout California to help protect the property and operations they’ve worked hard to build.
Before winter weather arrives, it’s a good time to review both your property and your insurance program. A little preparation now can make a very big difference when the rain starts falling.
Coming next week: Part 2 — The Storm Is Here: Protecting Your Home, Farm & Business During Heavy Rain, Flooding and Power Outages.
This article is provided for general informational purposes only. Insurance coverage varies by policy, carrier, circumstances and applicable terms, conditions and exclusions. Contact Scurich Insurance Services to discuss your specific insurance needs and coverage.
Read more
The FIFA World Cup is finally here, and soccer fans around the world are gathering with family and friends to cheer on their favorite teams. Whether you’re hosting a backyard barbecue, a poolside viewing party, or a living room packed with fellow fans, it’s worth taking a few minutes to think about safety and insurance before the first whistle blows.
At Scurich Insurance Services, we want our clients to enjoy the excitement of the tournament while protecting what matters most.
When Guests Come Over, Liability Matters
Most homeowners insurance policies include personal liability coverage that may help if someone is injured on your property. While nobody expects an accident during a World Cup celebration, larger gatherings can increase the likelihood of incidents such as:
- Slips and falls
- Injuries around swimming pools
- Dog-related incidents
- Damage to a guest’s property
- Accidents involving outdoor games or activities
Keeping walkways clear, securing loose cords, and supervising pool areas can help reduce risks.
Planning to Serve Alcohol?
Many watch parties include food, drinks, and plenty of cheering. However, alcohol can increase the potential for accidents.
While every situation is different, California homeowners should understand that liability can become complicated if a guest causes injury or property damage after leaving a gathering.
Encouraging designated drivers, rideshare services, and responsible consumption can help everyone get home safely.
Don’t Forget Your Backyard
Summer and World Cup season often go hand in hand. Backyard gatherings can involve:
- Barbecues
- Fire pits
- Trampolines
- Swimming pools
- Outdoor televisions and electronics
Taking a few simple precautions before guests arrive can help prevent injuries and property damage.
Consider an Umbrella Policy
Many homeowners are surprised to learn how affordable personal umbrella coverage can be.
An umbrella policy provides an extra layer of liability protection above the limits of your homeowners and auto insurance policies. For families who frequently entertain guests or simply want additional peace of mind, umbrella coverage may be worth discussing with their insurance professional.
Enjoy the Beautiful Game
The FIFA World Cup is one of the world’s most celebrated sporting events. It’s a time for friends, family, and communities to come together and enjoy the excitement of international competition.
If you have questions about homeowners insurance, personal liability protection, or umbrella coverage, the team at Scurich Insurance Services is happy to help.
From all of us at Scurich Insurance Services, enjoy the matches and have a safe World Cup season!
Read more
Trusted Insurance Solutions in Santa Cruz County – Protecting Your Business, Farm & Family
 Living and working in Santa Cruz County offers incredible opportunities—but it also comes with unique risks. From coastal weather exposures to agricultural operations and growing local businesses, having the right insurance coverage is essential. At Scurich Insurance Services, we help individuals, families, and business owners in Watsonville and surrounding communities protect what matters most.
With access to over 50 top-rated insurance carriers, we provide customized coverage solutions designed to fit your specific needs—not a one-size-fits-all policy.
Comprehensive Insurance Solutions for Santa Cruz County
Whether you’re running a business, managing a farm, or protecting your home and family, Scurich Insurance Services offers a full range of coverage options:
- Commercial Insurance Packages – Tailored policies that combine general liability, property, and other essential protections
- Farm & Agricultural Insurance – Specialized farm packages with potential Farm Bureau discounts
- Workers’ Compensation – Protect your employees and stay compliant with California regulations
- Professional Liability – Coverage for service-based businesses facing errors & omissions risks
- Umbrella Insurance – Additional liability protection beyond standard policy limits
- Group Benefits – Group health, life, and employee benefits to attract and retain talent
- Personal Insurance – Auto, home, life, and health coverage for individuals and families
Local Expertise That Makes a Difference
Insurance isn’t just about policies—it’s about understanding risk. Our team works closely with you to evaluate your exposures and build a smart risk management strategy. Whether you’re a small business owner, a contractor, or part of Santa Cruz County’s agricultural community, we bring local knowledge and industry insight to every recommendation.
We understand the challenges faced by businesses in Watsonville, Aptos, Santa Cruz, and surrounding areas—from liability concerns to employee coverage and long-term planning.
Why Choose Scurich Insurance Services?
- Access to 50+ insurance carriers for competitive options
- Customized coverage strategies based on your unique needs
- Local expertise in Santa Cruz County industries
- Risk management guidance beyond just selling policies
- Responsive, relationship-driven service
Protect What You’ve Built
Your business, your farm, your home – these aren’t just assets. They represent years of hard work and dedication. Having the right insurance coverage ensures you’re prepared for the unexpected while positioning yourself for long-term success.
At Scurich Insurance Services, we don’t just provide insurance—we help you plan wisely, reduce risk, and move forward with confidence.
Serving Watsonville & All of Santa Cruz County
We proudly serve clients throughout Watsonville and the greater Santa Cruz County area. Whether you’re reviewing your current policies or starting fresh, our team is ready to help you find the right protection at the right price.
Contact Scurich Insurance Services today to review your coverage and discover better options tailored to your needs.
Frequently Asked Questions
What types of insurance does Scurich Insurance Services offer?We offer a full range of insurance solutions including commercial packages, farm insurance, workers’ compensation, professional liability, umbrella coverage, group benefits, and personal insurance such as auto, home, life, and health.
Do you serve businesses in Watsonville and nearby areas?Yes. We proudly serve Watsonville, Santa Cruz, Aptos, and surrounding communities throughout Santa Cruz County with tailored insurance solutions and risk management support.
Can you help with farm and agricultural insurance?Absolutely. We specialize in farm insurance packages and can help identify Farm Bureau discount opportunities, liability protection, property coverage, and workers’ compensation for agricultural operations.
Why should I work with an independent insurance agency?As an independent agency, we represent over 50 insurance carriers. This allows us to compare options and customize coverage that best fits your needs, rather than offering a single carrier solution.
Do you provide risk management guidance?Yes. Beyond insurance policies, we help clients evaluate risks, plan strategically, and make informed decisions to better protect their business, farm, and personal assets.
Looking for better protection? Let Scurich Insurance Services help you build a smarter insurance strategy today.
Read more
What Central Coast Businesses and Homeowners Need to Know
The Central Coast has seen its share of intense weather in recent years — from heavy winter storms and localized flooding to coastal surge events and wind damage. Communities in Aptos, Santa Cruz, Monterey, and Salinas continue to feel the impact of shifting weather patterns that bring stronger storms and longer recovery periods.
For homeowners, landlords, contractors, agricultural operations, and business owners, now is the time to review insurance coverage and ensure you’re protected before the next storm hits.
At Scurich Insurance Services in Aptos, CA, we work with families and businesses throughout Santa Cruz County and Monterey County to help them prepare for real-world risks — not just theoretical ones.
Why Storm & Flood Risk Is Increasing on the Central Coast
Recent weather patterns have brought:
-
Heavier-than-normal rainfall totals
-
Flooded roadways and low-lying neighborhoods
-
Mudslides and erosion near burn scar areas
-
Wind damage to homes and commercial properties
-
Agricultural field saturation in the Salinas Valley
Coastal communities like Aptos and Santa Cruz are particularly vulnerable to:
Meanwhile, areas in Monterey and Salinas often face:
Even properties that have “never flooded before” have experienced water intrusion in recent seasons.
Does Your Homeowners Insurance Cover Flooding?
This is one of the biggest misconceptions we see.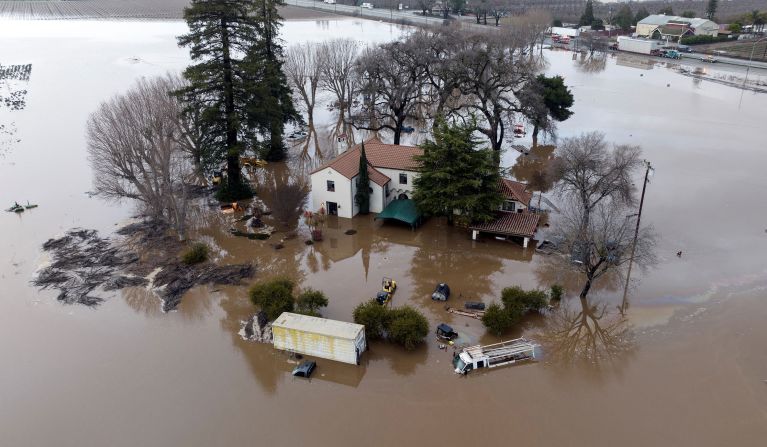
Standard homeowners insurance does NOT cover flood damage.
Flood insurance typically requires a separate policy. This applies whether you live:
-
Near the coast in Aptos or Santa Cruz
-
Near the Salinas River
-
In lower-elevation areas of Monterey
-
In inland agricultural zones
If water enters your home from rising ground water, storm runoff, or overflowing creeks — that is generally considered flood damage.
Without a flood policy, repairs can come entirely out of pocket.
What Homeowners Should Review Right Now
If you own a home in Santa Cruz or Monterey County, review:
1. Dwelling Coverage Limits
Are your rebuild limits updated for today’s construction costs?
2. Sewer & Drain Backup Coverage
Storm systems can overwhelm municipal infrastructure. This endorsement can be critical.
3. Flood Insurance Options
Even moderate-risk zones may benefit from coverage.
4. Deductibles
Some policies have percentage deductibles for wind or named storms.
5. Landscaping & Outbuildings
Retaining walls, detached garages, fencing, and outdoor structures may have limited coverage.
Business Owners: Storm Risk Is More Than Just Property Damage
If you operate a business in Aptos, Santa Cruz, Monterey, or Salinas, storms can disrupt:
Important Coverage Areas to Review:
Commercial Property Insurance
Protects buildings, improvements, and contents.
Business Interruption Insurance
Helps replace lost income if you must temporarily close.
Equipment Breakdown Coverage
Covers electrical systems damaged by power surges or outages.
Flood Insurance for Commercial Property
Separate from standard commercial property policies.
Agricultural & Winery Considerations in Monterey & Salinas
The Salinas Valley is one of the most productive agricultural regions in the country. Excessive rain, wind, and flooding can impact:
-
Crops
-
Irrigation systems
-
Equipment
-
Storage facilities
-
Access roads
Specialized agricultural coverage and crop insurance programs may be necessary to properly protect operations.
Coastal Property Risks in Aptos & Santa Cruz
Properties near the ocean face additional exposure to:
-
Salt air corrosion
-
Elevated wind exposure
-
Coastal erosion
-
Wave surge
Insurance carriers evaluate proximity to the coastline carefully. Premiums and deductibles may vary significantly based on location.
Working with a local agency that understands Central Coast geography can make a real difference in proper policy placement.
Why Local Experience Matters
Insurance isn’t one-size-fits-all — especially in areas with unique weather and geographic conditions like Santa Cruz and Monterey counties.
A local agency understands:
-
Neighborhood-specific flood patterns
-
Coastal wind zones
-
Agricultural exposures
-
Construction cost trends in the region
-
Carrier appetite changes after major storm seasons
At Scurich Insurance Services in Aptos, CA, we take a proactive approach — reviewing policies before problems arise.
Storm Preparedness Checklist
Before the next major weather event:
-
✔ Review your insurance policies
-
✔ Confirm flood coverage (if needed)
-
✔ Document property with photos
-
✔ Clear drainage systems and gutters
-
✔ Secure outdoor furniture and equipment
-
✔ Create a business continuity plan
Preparedness reduces both physical damage and financial stress.
Protect Your Property Before the Next Storm
Storm seasons on the Central Coast have become less predictable. Waiting until a major system is forecasted is often too late — especially for flood coverage, which may have waiting periods before activation.
If you live or operate a business in:
-
Aptos
-
Santa Cruz
-
Monterey
-
Salinas
-
Watsonville
-
Capitola
-
Carmel
Now is the right time for a coverage review.
Contact Scurich Insurance Services – Aptos, CA
Whether you’re protecting your home, business, rental property, or agricultural operation, our team can help you evaluate options and identify coverage gaps.
Insurance is about preparation — and preparation starts before the storm clouds gather.
Read more
Super Bowl Sunday is one of the biggest entertaining days of the year. From packed living rooms and big-screen TVs to food, drinks, and cheering guests, it’s a great time to bring people together. But hosting a Super Bowl party also comes with responsibilities — and potential insurance risks many homeowners overlook.
At Scurich Insurance Services, we help homeowners understand how their insurance coverage applies when hosting gatherings like Super Bowl parties. Here’s what you should know before kickoff.
Homeowners Liability Coverage When Hosting a Super Bowl Party
When guests are invited into your home, your homeowners or renters insurance typically provides personal liability coverage if someone is injured on your property. This coverage may help pay for medical expenses, legal defense, and damages if you’re found responsible.
Common Super Bowl party claims can include:
-
Slip-and-fall injuries from spilled drinks or crowded areas
-
Accidental injuries during celebrations
-
Property damage to or caused by guests
-
Claims related to unsafe conditions inside or outside the home
Coverage limits vary, and serious injuries can exceed standard policy limits — making it important to review your protection ahead of time.
Alcohol & Social Host Liability Risks
Alcohol is often part of Super Bowl celebrations, but serving alcohol increases your exposure to liability. In certain situations, a host may be held responsible if an intoxicated guest causes injury or property damage after leaving the party.
To reduce risk:
-
Serve food and provide non-alcoholic beverages
-
Avoid over-serving alcohol
-
Stop alcohol service well before the end of the party
-
Encourage ride-shares, designated drivers, or overnight stays
Some homeowners policies offer limited protection for hosting events, but coverage details differ by policy and situation.
For additional guidance, see:
https://www.scurichinsurance.com/super-bowl-party-considerations-before-serving-alcohol-to-party-guests/
Preventing Common Super Bowl Party Accidents
Simple precautions can significantly reduce the chance of injuries and insurance claims:
-
Keep walkways, hallways, and entry areas clear
-
Secure loose rugs, cords, and decorations
-
Clean spills promptly
-
Move fragile or valuable items out of high-traffic areas
Accident prevention protects both your guests and your financial well-being.
Is Your Liability Insurance Enough?
Standard homeowners and renters insurance includes liability coverage, but limits may not be sufficient if a serious injury occurs. Medical bills and legal costs can escalate quickly.
A personal umbrella insurance policy can provide additional liability protection beyond your homeowners or auto insurance limits. For homeowners who frequently entertain, this extra layer of coverage can be a smart and affordable safeguard.
Talk to Scurich Insurance Services Before Game Day
Before hosting your Super Bowl party, take a few minutes to review your insurance coverage. Scurich Insurance Services can help you understand your homeowners or renters policy, evaluate liability limits, and identify coverage gaps — so you can host with confidence.
Contact Scurich Insurance Services today to schedule a coverage review or discuss liability protection options.
Enjoy the game, enjoy your guests, and let your insurance coverage work quietly in the background — exactly where it belongs.
Read more
10 months ago
·
by
Erin Carlson ·
0 comments
 The Central Coast has always been resilient, but the past few months have reminded all of us how quickly conditions can change. Between heavy winter rains, localized flooding, ongoing road closures, and shifting wildfire risks, residents and businesses across Aptos, Watsonville, and the greater Monterey region have faced another season of unpredictable weather.
At Scurich Insurance Services, our roots in this community run deep. We’ve helped families, farms, and small businesses navigate these challenges for decades — and we want to share a quick update on what’s happening locally and how you can stay protected.
Recent Local Conditions Worth Noting
1. Heavy Rains & Flooding Concerns (Especially in Low-Lying Watsonville Areas)
Recent storm systems brought saturated soils and rising creek levels across the Pajaro Valley. While major flooding has been limited compared to past years, several rural roads saw pooling, and the potential remains when additional storms roll through.
Insurance Tip:
Review your homeowner’s or business policy for flood exclusions. Standard policies do not cover groundwater or floodwater damage. Flood insurance must be purchased separately and often carries a waiting period.
2. Coastal Impacts in Aptos
High surf advisories and bluff erosion have once again affected coastal roads and properties in Aptos. Even residents inland are feeling the effects through road impacts, power outages, or delayed services.
Insurance Tip:
If you live near the coast or own a rental home there, consider reviewing:
-
Extended replacement cost coverage
-
Earth movement/landslide endorsements
-
Loss of use or rental income coverage
These small additions can make a big difference during storm season.
3. Monterey County Agriculture Still Recovering
The storms have continued to impact farm access, equipment storage, and seasonal planting schedules. Operators across Watsonville, Salinas, and Monterey County are recalibrating for 2025.
Insurance Tip:
Agribusiness owners should take time now to review:
Unexpected downtime is one of the largest financial risks a farming operation faces.
4. Wildfire Preparations Restart Soon
Although winter moisture reduces immediate fire danger, spring and summer wildfire planning begins now. Many insurance carriers are updating underwriting standards in Santa Cruz and Monterey Counties.
Insurance Tip:
If you received a non-renewal or premium increase, reach out early — options exist, but they fill up fast as the season approaches.
How Scurich Insurance Services Can Help Today
As your local, independent insurance partner, we offer:
-
Free policy reviews for homeowners, renters, farms, and businesses
-
Flood insurance and excess flood options
-
Access to multiple carriers (not just one) so we can shop for the best rate
-
Guidance on disaster documentation and preparedness
-
Claims support you can rely on when it matters most
Whether you live near the coast in Aptos, operate a business in Watsonville, or manage a property anywhere in Santa Cruz or Monterey counties, we’re here to help you stay protected through every season.
Have Questions About Your Coverage?
We’re local, we’re here, and we’re ready to help.
Contact Scurich Insurance Services today.
Phone: (831) 722-3541
Website: www.scurichinsurance.com
Stay safe — and thank you for trusting us to protect what matters most.
Read more
