 In today’s “litigation society,” you face lawsuits that could cripple your bottom line – or even put you out of business – based on anything from a fire on your premises to an allegation of libel by a competitor.
Commercial General Liability (CGL) insurance provides financial protection against damage or injury caused by something that your business did, or perhaps didn’t do.
Your CGL policy covers a variety of exposures:
- Premises and Operations Legal Liability pays for injuries or property damage on your premises, as well as those that occur outside your place of business.
- Products and Completed Operations Legal Liability covers injury or property damage resulting from someone using your products, or real or alleged faults as a result of work your business has completed.
- Fire Legal Liability pays for injuries and damage from fires for which your business is responsible or that started due to your negligence.
- Personal and Advertising Injury protects your business against litigation alleging libel, slander, or invasion of privacy.
- Host Liquor Legal Liability will pay for lawsuits from hosting a party or special event at which you serve alcohol and intoxicated people cause injuries or property damage.
- Medical Payments covers bills when your customers, suppliers, or visitors suffer bodily injury on your premises, or resulting from your operations offsite.
To learn more about this essential coverage, just give us a call at Scurich Insurance Services today!
Read more
 If you’re using “contingent workers” — on a part-time, temporary, or contract basis — be aware that these employees face a greater risk of occupational injuries and illness. According to the National Institute for Occupational Safety & Health (NIOSH) reasons for this higher vulnerability include the tendency to outsource more hazardous jobs, lack of experience and familiarity with operations in a dangerous workplace, inadequate protective equipment, and limited access to such preventive measures as medical screening programs. The chances are that temporary workers have a wide variety of experience levels (due to high turnover) or have had the benefit of formal safety programs.
Also, bear in mind that even though the safety of contract workers is the legal responsibility of the contractor, the OSHA General Duty Clause could be interpreted to make you responsible for protecting everyone in your workplace. To help meet this obligation, and bolster workplace safety compliance we’d recommend that you take these steps:
- Include safety requirements in the contract, even if only to state that the contractor must comply with OSHA requirements. If the contractor doesn’t follow safety rules, you can force compliance or stop work for breach of contract.
- Set the safety compliance ground rules up front, during orientation or before they start work.
- Share accountability. Although an accident caused by a contract worker might not be your legal responsibility, it’s still your problem. Don’t leave safety compliance problems for the contractor to solve alone.
- Offer assistance. Explain all hazardous conditions or processes during the initial project orientation and stress any rules and restrictions, such as hot-work permit requirements, lockout/tagout, and confined spaces situations and needs.
- Document communications with contractors. Give the contractor(s) a document or form to sign when resolving specific safety problems or for conducting inspections.
- Read the OSHA Multi-Employer Citation Policy. OSHA published an enforcement and compliance directive (CPL 02-00-124, December 10, 1999) laying out its citation policy for multi-employer worksites, which includes contractors.
Finally, don’t forget that most contingent workers will only be in your workplace for a relatively short time. This only adds to the urgency of getting them up to speed on your company’s safety policies and practices as quickly as possible.
Contact our office today for more information.
Content provided by Transformer Marketing.
Read more
 Plumbers, electricians, carpenters, tree surgeons and roofers who perform skilled work on a customer’s premises are just a few examples of artisan contractors. These workers are also called casual contractors. Piano tuners, interior decorators, exterminators and other skilled service providers are also considered artisan contractors. These contractors require special insurance for their tools and equipment, which are commonly moved from one site to another until each job is finished. The most affordable and efficient way for an artisan contractor to get liability and property coverage is to obtain a Business Owners Policy that is tailored to fit individual needs. Although they might be marketed under varying names, such policies usually have similar terms.
Property owned by the business and real property are covered by the BOP. The property must be located at the address of the business described in the policy. Businesses that lease or rent their locations have coverage from the BOP for tenants’ betterments and improvements. These include any installations, additions or alterations that cannot legally be taken away from the premises. Equipment that moves from one site to another and valuable machinery are items that pose the greatest risk for a significant loss. Such items are not covered under a standard property insurance policy. These items are classified as movable property, which means special contracts are required to obtain insurance. These special contracts are called floaters.
Various types of equipment and machinery are covered during transit with an installer’s floater. They’re also covered during testing. In some cases, building materials might also be covered. Policies may be written to include coverage on a reporting form or for a single job. This means that the contractor provides information to the insurer regarding each new contract. Tools and equipment floaters provide coverage for the property that is insured. Coverage is extended to any location where the movable property is used.
Liability coverage is essential for all contractors. If a customer files a lawsuit, this type of coverage will certainly be required to protect the contractor. Subcontractors’ customers might require individuals who work for them to have Owners and Contractors Protective Liability insurance. This type of coverage provides protection for business owners from liabilities resulting from negligent acts committed by contractors or subcontractors. It’s best to speak with one of our agents to learn how this type of coverage works. There might also be coverage for certain vehicles. Speak with us to learn what types of coverage are available for vehicles that are used primarily for business.
Content provided by Transformer Marketing.
Read more
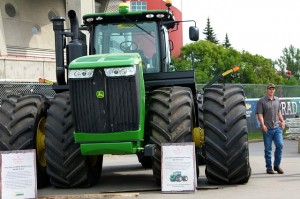 Our next Second Saturday On The Farm is on Saturday, March 8, 11 am – 3 pm at the Santa Cruz County Fairgrounds, Highway 152 outside Watsonville. This event is FREE! Donations appreciated. Bring your whole neighborhood to participate!
This Second Saturday on the Farm features a scheduled talk on how robots are used in the agriculture industry in Santa Cruz County and around the world, plus LEGO building, robotic car races, programming, drawing a robot, competing sumo robots, hayrides, movies, practice cow milking, and other activities for children.
11:00 am – 3:00 pm: LEGO building, Robotic car races, Programming a BeeBot robot, drawing a robot, Sumo robotics, and other fun activities for children.
1:00 pm – 1:30 pm: Learn to Discover, an educational nonprofit organization, will be discussing Robots in the Agriculture Industry.
Ongoing: Our popular tractor driving, practice cow milking, water pumping, and other fun activities for kids.
Brian and Shelly Laschkewitsch from Learn to Discover will be facilitating many of the fun learning activities about robotics at this event.
Learn to Discover is a 501 c(3) nonprofit that designs, develops and delivers high-quality, hands-on STEAM (Science, Technology, Engineering, Art & Math) courses and activities to kids from pre-school through high-school.
Content provided by http://www.aghistoryproject.org/event/second-saturday-farm-robotics-agriculture/
Read more
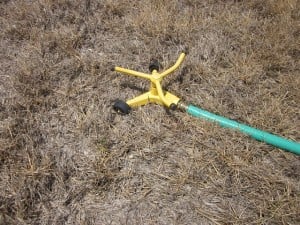 Farmers in California, where Gov. Jerry Brown declared a state of emergency last month, are facing hard choices as a drought threatens to ruin their crops. They must weigh the costs of paying for irrigation against the chance that their fields will never get enough water this season.
A striking picture illustrates the severity of the situation, as Northern California’s Folsom Lake, a reservoir northeast of Sacramento, is seen in January at only 17 percent of its capacity. In July 2011, “the lake was at 97 percent of total capacity and 130 percent of its historical average for that date,” according to NASA.
The federal agency says it is working with the California Department of Water Resources to help the state manage its water resources. Last month, NASA released other images showing the drought’s severity. As NPR member station KQED reported, the state’s snowpack is shown in January 2013 and last month. Much of it did not return.
Here are other updates on the situation:
NASA said today that it’s working to share satellite and weather data with California farmers and water officials to help them avoid wasting water, and to use it in the most efficient way possible. The space agency says a trial run of its Satellite Irrigation Management Support system in 2012 and 2013 “demonstrated sustained yields while reducing the amount of water used by up to 33 percent relative to standard practice.”
Growers of almonds — a state crop valued at $5 billion in 2012 — have been pulling trees out of the ground while they’re still in their prime, in desperate actions driven by high water costs. The AP spoke to a grower who watched crews rip 20 percent of his orchard out of the ground. A man who does that work for a living says business is up 75 percent because of the drought, and his crews are working from sunup to sundown.
Forecasts of rain and snow were welcomed by many Californians, as parts of the state could see more rain this week than they’ve had in the previous eight months together. But Time’s Bryan Walsh warns that even with that rainfall, “much of California will still be below average for precipitation this month. Since February tends to be the wettest month for California, that means that the state still has a larger and larger rainfall deficit to make up if this drought is to ever end.”
Contact Scurich Insurance Services today to get a review of your agriculture insurance.
Content provided by http://www.npr.org/blogs/thetwo-way/2014/02/25/282624536/california-s-drought-a-shocking-photo-and-other-updates
Read more
 I recently did a workshop for a group of CEOs at which the Chair asked the participants, “What single piece of wisdom have you learned about managing people?” Here are some of their responses:
Don’t try to manage more than seven reports at a time.
Be firm, but fair.
Focus on the problem and not the person.
Never look a gift resignation in the mouth.
Be direct; people want the truth and nothing but the truth.
Tap into the company’s informal communication network.
Don’t take things personally (one of Don Miguel Ruiz’s Four Agreements).
Never take sides.
Listen (can you listen to someone for five minutes straight without any interruption, criticism, or judgment?).
Be slow to hire and fast to fire (a popular topic in the workshop!).
Bear in mind that a decision driven by emotion, is not driven by logic (or, as I like to say, if it doesn’t make sense, don’t try to make sense out of it!).
Content provided by Transformer Marketing and http://humanresources.about.com/od/icebreakers/a/icebrker_wisdom.htm
Read more

 In today’s “litigation society,” you face lawsuits that could cripple your bottom line – or even put you out of business – based on anything from a fire on your premises to an allegation of libel by a competitor.